


- 'Is democracy in India being undermined like China, Russia and North Korea': Gehlot on FIR against Rahul, Priyanka Gandhi
- Delhi Seemapuri Building Collapse: Several Feared Trapped As Rescue Operation Underway
- Claude Users Can Work Across Google Docs, Sheets and Slides In-App
- Rapido Ride Turns Into Nightmare After Captain Flees With Injured Passenger
- 7 Must-Watch OTT Releases For Your Dussehra Holidays
- ‘His Lips Turned Blue’: Dentist Recalls 45-Minute Effort To Save Flydubai Pilot Smit Machchhar
- Airtel Postpaid Plans Bring Free International Roaming From Rs 499
- 'Politics means nation building to him': Rajnath Singh on PM Modi's 25 years in public service
Doing nothing strategy can beat hyperactive investing
In Short
Equal-weight portfolios outperformed over the long run, while concentrated bets on large stocks proved less reliable
Share :
Doing nothing strategy can beat hyperactive investing
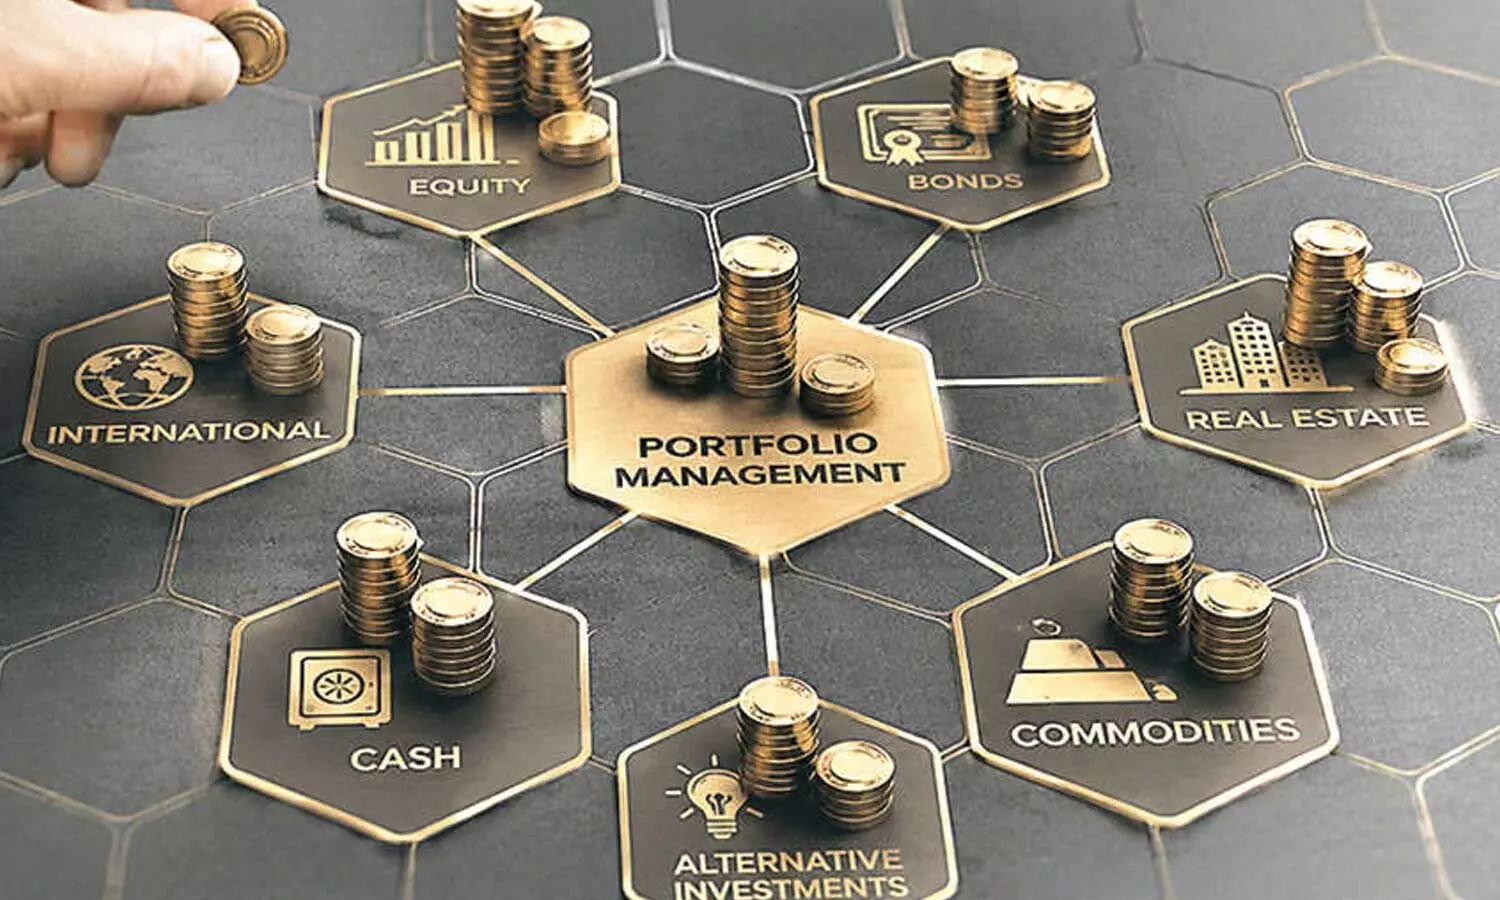
Theinvesting world at times behaves in ways that are counterproductive to the investing objectives. The financial media, particularly, encourages higher activity (buying/selling) knowing very well that its detrimental for long term wealth creation. Doing nothing is highly underrated in this hyperactive world. In a recent paper, Hendrik Bessembinder analyzed the performance of ‘do nothing’ portfolio which illustrates how portfolios would’ve performed simply by holding without making changes.
The study examines investors would have done better by holding on to those stocks that subsequently left the S&P 500, compared to investing in the S&P500 index. The study evaluates equal-weighted versus value-weighted portfolios, do-nothing portfolios versus the S&P500 index, portfolios of the largest stock versus all the index constituents, and narrow portfolios containing randomly selected stocks over holding periods of 1, 5 and 10years for the full 55-year period starting from 1971 till 2025.
The observation from the study shows that equal weighted portfolios outperformed value-weighted portfolios with $1 invested turns into $678 in 55years while value-weighted turned the $1 into $361. The mean 1- year return being 14.02% for equal weighted portfolios versus 12.69% for value-weighted portfolio.
These observations boost the equal weight strategies over market cap strategies. In the one-year comparison mentioned above, the portfolios are rebalanced back to target weights at the end of the year, making the do-nothing a misnomer. He suggests that the small cap effect could be a reason for the superior performance. Unlike the market cap approach where the weightage fluctuates with the stock’s performance, the equal weighted portfolios have the targeted allocations fixed. Thus, the rebalancing has significant impact on this portfolio’s performance. But the performance gap between these two narrows with $1 initial investment turning to $397 versus $342 over the 10-year rebalancing cycle.
The do-nothing value-weighted portfolios essentially matched the S&P500 index returns. The mean return of value-weighted is at 12.69% versus 12.64% of the index. Over the 55-year period, $1 initially invested turned to $344 by the index versus $342 for the value-weighted do-nothing portfolio. The study thus states that there was no appreciable difference in compound outcomes over the period between these two portfolios.
The study highlights that average return and probability of success are different. A narrow portfolio can have an average return similar tothe index across many simulations, while still underperforming the index in majority of the actual outcomes. This is an important result of the study: the average outcome does not mean that a typical investor holding a narrow portfolio is equally likely to match or beat the index.
Another critical takeaway is that ‘do nothing’ doesn’t mean own one or two stocks forever. The study's evidence does not support the idea that an investor should randomly select a handful of stocks and simply hold them indefinitely. The study finds that narrow portfolios underperformed the index more often than not, particularly over longer periods. The study does, however, note that narrow portfolios may be appropriate for investors who genuinely possess skill in identifying mispriced securities, while alsohighlighting the risk of investors overestimating their skill.
The recent performance of the largest stocks was unusual over the full period. The study examines portfolios of the largest 100, 50, 10 and 1 stock, compared with portfolios containing all index constituents. As of mid-2026, the ten largest stocks accounted for 38% of the S&P500 index. It is indeed possible for the largest stocks to outperform substantially as they did from 2013 to the end of the sample. However, the study reports that this was not typical over the full 55-year period. Portfolios constructed from larger stocks underperformed over the full sample, particularly during the 1971–2013 period.
For example, over 55 years, the compound return per dollar initially invested was:100-stock portfolio: $339, 50-stock portfolio: $353, 10-stock portfolio: $333, Single-largest-stock portfolio: $179 and Value-weighted portfolio containing all constituent stocks: $342. The study therefore records substantially different outcomes depending on the period and the portfolio construction method.
The study shows that broad diversification doesn’t necessarily mean sacrificing returns. It finds that value-weighted “do-nothing” portfolios broadly matched the S&P 500 over the full 1971–2025 period. The implication from the study is that an investor did not generally need to continuously replace stocks simply because they left the index to achieve broadly similar long-term outcomes.
The study finds that concentration could work but recent success shouldn’t be extrapolated indefinitely. The largest stocks have performed exceptionally well in the recent period, especially from 2013 onward. But the study finds that this was not the typical historical experience: over the longer 55-year sample, portfolios concentrated in the largest stocks generally performed poorly relative to broader portfolios.
The study's evidence favours distinguishing between long-term diversification and short-term concentration narratives. The recent outperformance of the largest stocks is real, but the historical evidence does not show that concentration in the largest stocks has been a consistently superior strategy. At the same time, a broadly diversified, value-weighted portfolio held over time produced outcomes broadly comparable to the S&P 500, while narrower portfolios increased the likelihood of underperformance.
(The author is a partner with “Wealocity Analytics”, a SEBI registered Research Analyst firm and could be reached at [email protected])

India condemns attacks on commercial vessels in Black Sea, reiterates call for dialogue and diplomacy
'Is democracy in India being undermined like China, Russia and North Korea': Gehlot on FIR against Rahul, Priyanka Gandhi
SSB pays tribute to bravehearts killed in Maoist attack 15 years ago
SSB pays tribute to bravehearts killed in Maoist attack 15 years ago
Pixel Moments to Politics For Cong As BJP Celebrates Modi@25
Dramatic face-off near Jantar Mantar. Rahul and Priyanka sit on the road
MPs vs Police. Chaos and High Drama Unfold on Delhi Roads
Henri Kagan, Kenso Soai Win 2026 Nobel Chemistry Prize for Autocatalysis
AP cabinet approves 12 agenda items
High Courts should not suggest custodial interrogation of accused, says Supreme Court


